Wealth & Succession

If you stepped away tomorrow, who could say, on a single sheet of paper, what belongs to whom?

Almost every business owner has thought about "getting this organized someday". The day the organizing becomes urgent is exactly the day nobody is in a state to decide anything. The question that matters is not "when will I get organized". It is a different one: how much of your estate depends on you being present for it to keep working?

Who owns what, on a single sheet of paper
01Who owns what, on a single sheet of paper
Tax and court costs are paid in cash, not in hectares
02Tax and court costs are paid in cash, not in hectares
The conversation happens during your lifetime, with the numbers on the table
03The conversation happens during your lifetime, with the numbers on the table

Four questions that tend to come too late

How long could your family last with the estate frozen?

Inventário is the formal process of surveying what the person left, paying what they owed, collecting the tax and transferring the remainder to the heirs. Until it ends, the assets exist, but they barely move: as a rule you can't safely sell a property, operate an account or make decisions at the company without authorization. When the heirs are adults, legally capable, in agreement and there is no will, the extrajudicial route, by deed at a notary's office, is usually available and the path tends to be shorter. When there is a minor, an incapacitated person, a dispute or doubt about what belongs to whom, it goes to the courts, and the timeline stops depending on the family. The biggest cost is rarely the fee: it is the time the estate sits idle and the relationship between siblings turns sour. Have you ever done that calculation in months, not in reais?

Where would the money for the tax come from?

ITCMD is the state tax levied on inheritance and on gifts. State-level means the rate and the rules vary from state to state, within a national ceiling, and can change by law before you need them. There is no "Brazilian" rate: there is the one in your state, on the date of the event, which is why this page cites no number at all. It is paid in cash, normally before the asset is released. If your entire estate is in real estate, land or working capital, who sells what, and at what price, to pay that bill? Succession planning is as much a matter of cash as of structure. The rule currently in force is something your lawyer and your accountant confirm.

If twenty assets became one, who would decide for it?

A family holding is a company created to own the family's assets: real estate, stakes in other companies, sometimes investments. Instead of twenty assets in one person's name, there is one: the holding's shares (quotas). Two real gains follow from there. Governance: the articles of association and a shareholders' agreement define who decides, who can sell, what happens if an heir wants to leave, how a tie is resolved. Transfer during your lifetime: the estate can be donated in shares, often with the father and mother keeping the usufruct, that is, they continue to be in charge and to receive the income for as long as they live. What you gain is predictability: the rules were written by someone who was alive, lucid and present. Today, who would write yours?

Who told you a holding eliminates tax?

Donating shares during your lifetime is normally also a taxable event for ITCMD: in many cases you bring the tax forward, you don't eliminate it. Contributing real estate to the company involves a valuation, ITBI (the municipal property transfer tax) in certain situations, and an effect on capital gains when the asset is sold later; each case has its own design and its own cost. A holding also doesn't protect against debt you already have: a structure built to shield a known creditor tends to be undone in court. And a holding doesn't fix a family: if the siblings don't speak to each other, it only moves the fight from the probate court to the shareholders' meeting. Before asking "holding or not", it is worth asking: is the problem I want to solve one of tax, governance, liquidity or conversation?
The questions the family never asked during your lifetime

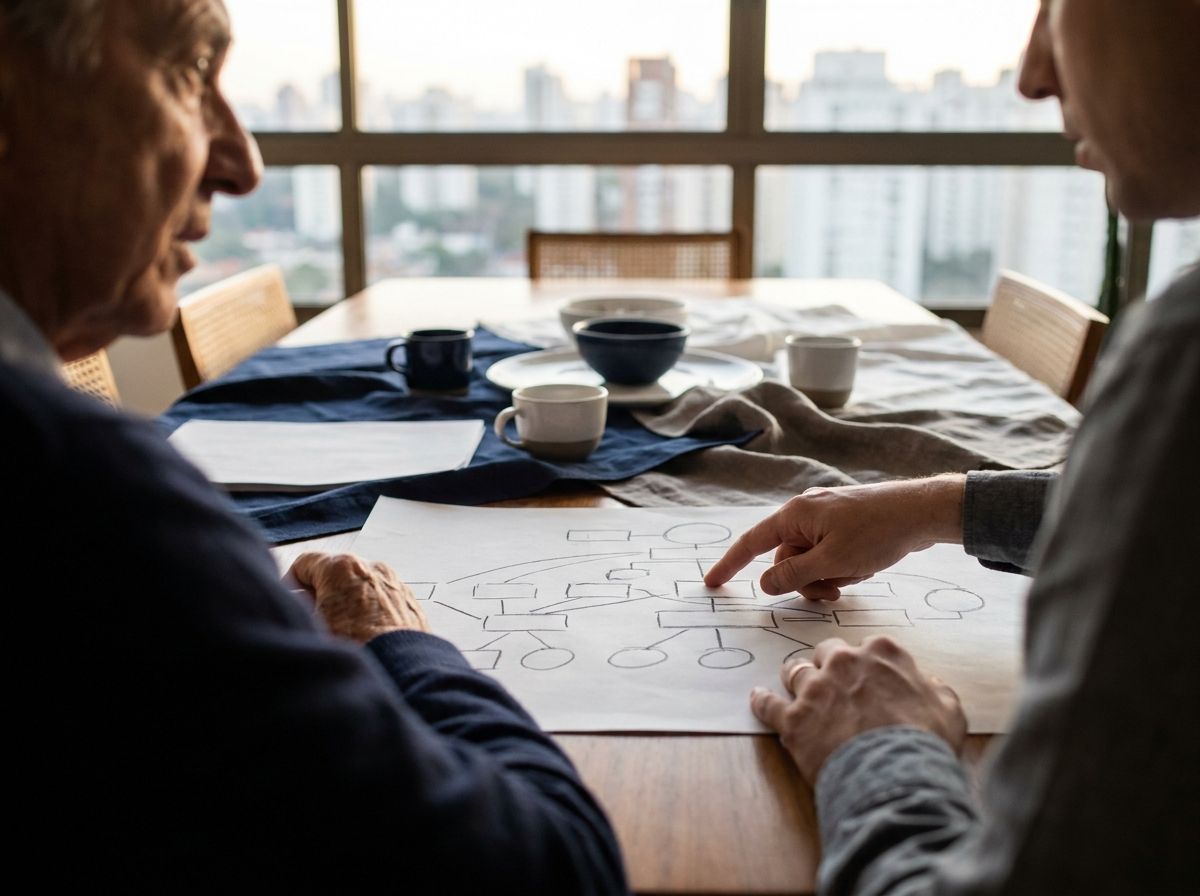
When was the last time someone put your entire estate on a single sheet of paper and asked what would happen to it in your absence? Not to sell a structure: to see what exists. If the answer is "never", that is the most common scenario among people who have built wealth over twenty or thirty years. Five questions are worth more than they seem:

  • Who owns what today: an individual, a company (CNPJ), a property in a child's name? Can you draw it on a sheet of paper?
  • If you stepped away, who signs for the company on Monday, and with what authorization?
  • How much idle cash exists for tax, court costs and the time the estate is frozen, without selling assets in a hurry?
  • Do your heirs want the same thing? One wants to run the company, another wants the money, the third lives abroad. Have you talked about it with the numbers on the table?
  • Do pension plans, life insurance and assets abroad fit into this picture, or does each one live in isolation?

If three of these questions went unanswered, the planning doesn't exist yet. There is an intention.

What I do in this conversation

  • I map the estate as it really is before any structure: what exists, where it is, in whose name, how much income it generates, how much liquidity it has. Many families discover things in that spreadsheet that they didn't know.
  • I calculate the liquidity needed for the succession event: how much would have to be available for tax, court costs and the time the estate is frozen, so that nobody has to sell assets in a hurry.
  • I explain each financial tool that tends to come into this conversation (life insurance, pension plans, liquid assets, assets abroad), including limitations and costs. Explaining is not recommending: what makes sense depends on your case.
  • I work together with your lawyer and your accountant. They design and carry out the legal and tax structure; I take care of the financial side. If that team doesn't exist yet, my recommendation will be to build it first, rather than improvise.
  • I translate the design for the family: the conversation between parents and children takes place in a room, with the numbers on the table, while it is still possible to change your mind.
  • I follow up over time. A child is born, a partner leaves, a company is sold, a state law changes. A succession structure without review ages badly.

The limit of this work

I am not a lawyer. I don't set up holdings, I don't draft articles of association, I don't write wills (testamento), I don't issue tax opinions and I don't state what your ITCMD rate will be ten years from now: that is the job of those who hold a OAB license (the Brazilian Bar Association registration) and of those who handle your accounting. What I do is the financial part: estate diagnosis, liquidity, portfolio, products and follow-up, sitting at the table with your legal team. The funds are held in custody at BTG Pactual, under your CPF (individual taxpayer ID) or the CNPJ (company taxpayer ID) of the structure, and the decisions remain yours. And there is a bigger limit: succession planning reduces friction, tax at the wrong moment and paralysis; it does not eliminate tax or replace an agreement between people. Anyone who promises total shielding is selling something else.

Frequently asked questions

Is a holding worth it for any estate?

No. A holding has setup costs, maintenance costs, accounting and obligations of its own: it exists every month, not only on the day of succession. For some estates, the annual cost of the structure exceeds the problem it would solve. For others, the inventário would cost far more. This isn't answered by a rule of thumb: it is answered by comparing the numbers of your case, and the final decision goes through your lawyer.

If I create a holding, do I stop paying ITCMD?

No. Donating shares (quotas) during your lifetime is usually a taxable event for ITCMD all the same. In many situations the effect is to bring the tax forward and organize it, with predictability and under the rules in force today, instead of letting it fall on the family all at once at a bad time. The person who makes that calculation, with your state's law in hand, is your lawyer and your accountant; I help make sure there is cash available to pay the bill.

Does my pension plan go into the inventário?

The design of PGBL and VGBL (Brazilian private pension plans) provides for direct payment to the beneficiaries named in the policy, generally without waiting for the end of the division of the estate, which helps with liquidity at the moment the family needs it most. In December 2024 the STF (Brazil's Supreme Federal Court) ruled, in Theme 1,214, that levying ITCMD on that payout is unconstitutional. How this applies to your plan depends on beneficiaries, form of receipt and origin of the funds, and forced heirs and the legítima (the share of the estate reserved by law for them) still require legal analysis. The detail is on the pension page.

I'm healthy and 45 years old. Isn't this too early?

It is the right time, precisely for that reason. Succession planning can only be done by someone who is alive, lucid and not in a hurry. After that, it is no longer planning, it is inventário. And most of the benefit shows up during your lifetime: clarity about who decides what, an open conversation between partners and heirs, an organized estate.

I already have a lawyer and an accountant. Do you get in the way or add to the team?

I add, and I prefer it that way. My work doesn't compete with theirs: they take care of the legal and tax structure; I do the estate diagnosis, the liquidity calculation and the portfolio advisory within the BTG Pactual platform. You decide, and you carry out, each investment. The funds are held in custody at BTG, under your CPF or the CNPJ of the structure, never with me.

Do you already know what would happen to your estate in your absence?

If the answer took a while, that is why the first conversation exists: to put what you have on a single sheet of paper and see where the weak points are, if there are any at all. A structure, if it makes sense, comes later, designed with your lawyer and your accountant. No promise of shielding. With a diagnosis of what exists today.

The analysis takes into account the investor's individual characteristics and the applicable legislation. Legal structures, donations and decisions on ITCMD must be assessed case by case, with a lawyer and an accountant.